DIFC Commercial Tightness & Grade-A Yield Compression
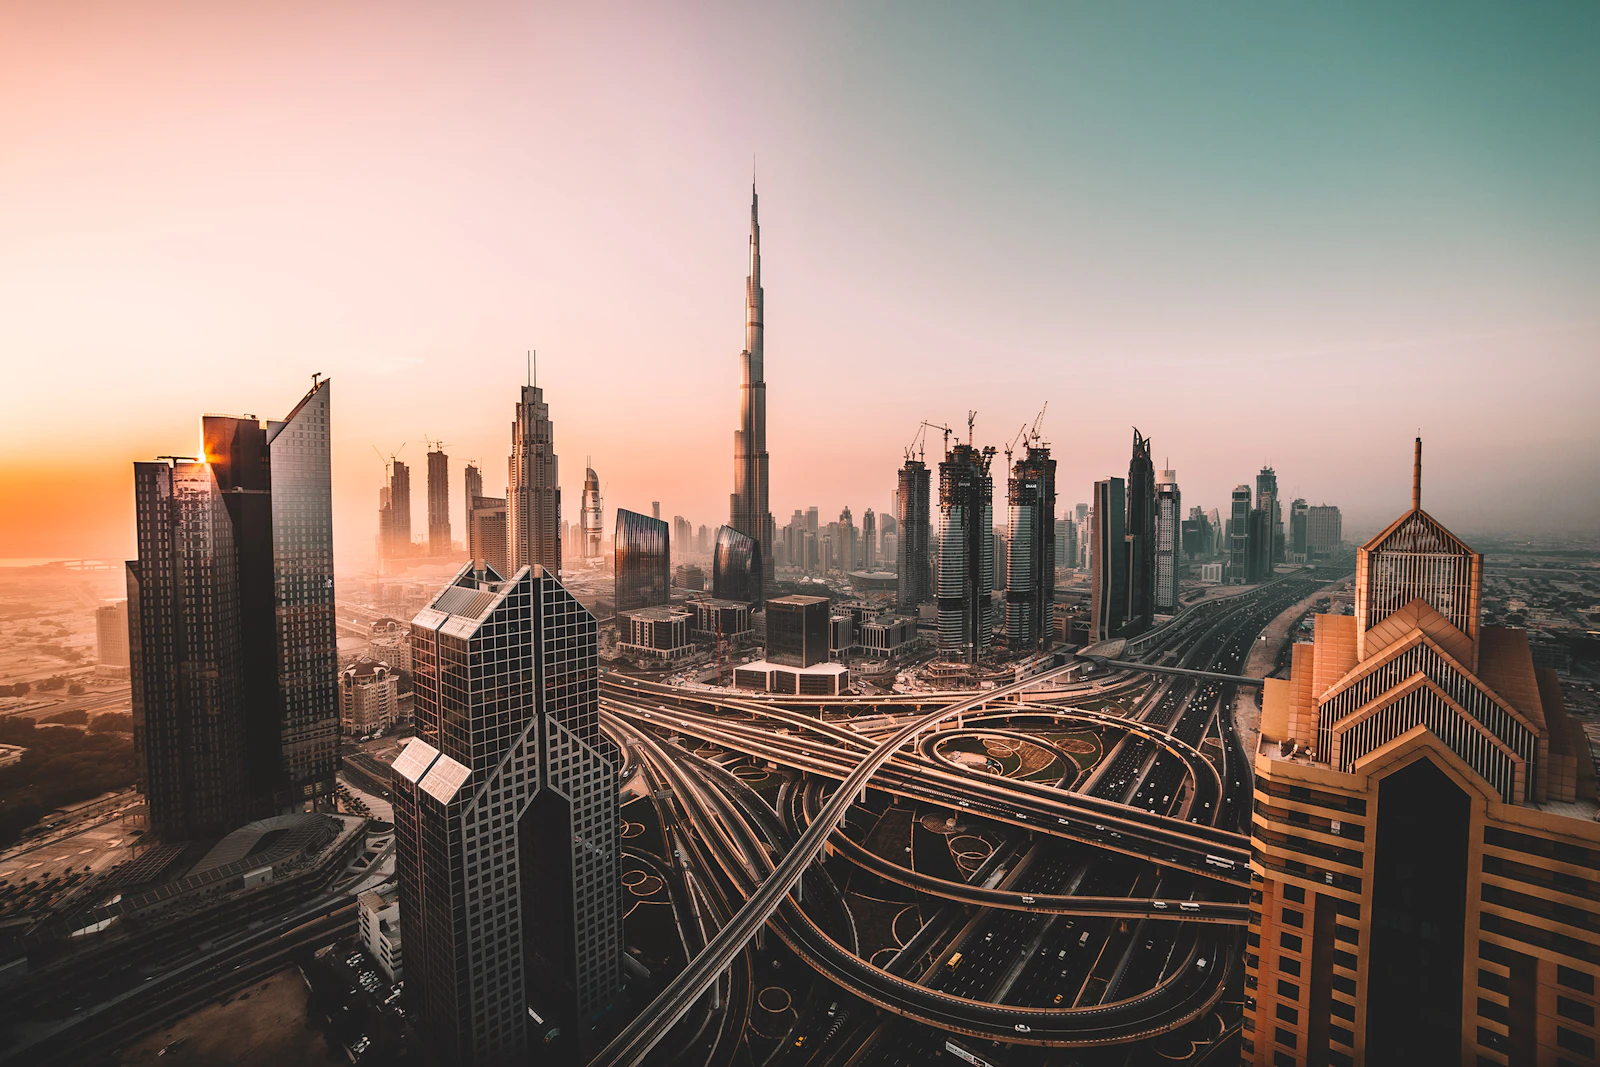
Written by Chak (Chakravarthy Natarajan Santhakumar) - Last updated: November 2026. The Dubai International Financial Centre continues to exhibit severe structural undersupply across core commercial strata, driven by relentless institutional inflows and a regulatory framework that commands immense global prestige. As multinational occupiers compete fiercely for limited footprints, vacancy rates within prime addresses have compressed to near-zero levels, creating an intensely landlord-favourable leasing environment.Sovereign capital corridors and international wealth funds are actively bidding up prime commercial assets, seeking safe-haven cash flows amidst broader macroeconomic uncertainties. This sustained demand pressure has directly accelerated capital values, resulting in aggressive yield compression across fully fitted Grade-A inventory. Traditional cap-rate calculations no longer apply when evaluating these trophy assets, as pricing increasingly reflects scarcity value and long-term strategic positioning.Master community maturity within the financial district has reached a saturation point where new contiguous land releases are virtually non-existent. Consequently, asset appreciation is decoupled from broader Dubai property cycles, tethered instead to tenant revenue density and the unwavering appeal of common law regulatory structures. Investors entering this sub-market must look past nominal headline prices and evaluate the structural durability of cash flows under shifting global tax regimes.This advisory note establishes a rigorous underwriting baseline for evaluating DIFC commercial acquisitions, dissecting the true operational drag on net operating income and stress-testing capital deployment against potential macroeconomic headwinds. Our objective is to strip away retail sales hype and provide institutional-grade clarity for family offices and private capital allocators deploying significant ticket sizes into Dubai's premier financial free zone.
)